You Served. Now Let’s Get You Home.
Houston is home to more than 250,000 veterans. We help them buy, sell, and put their VA benefits to work across Fort Bend County and the greater Houston area.
More Than Just Realtors
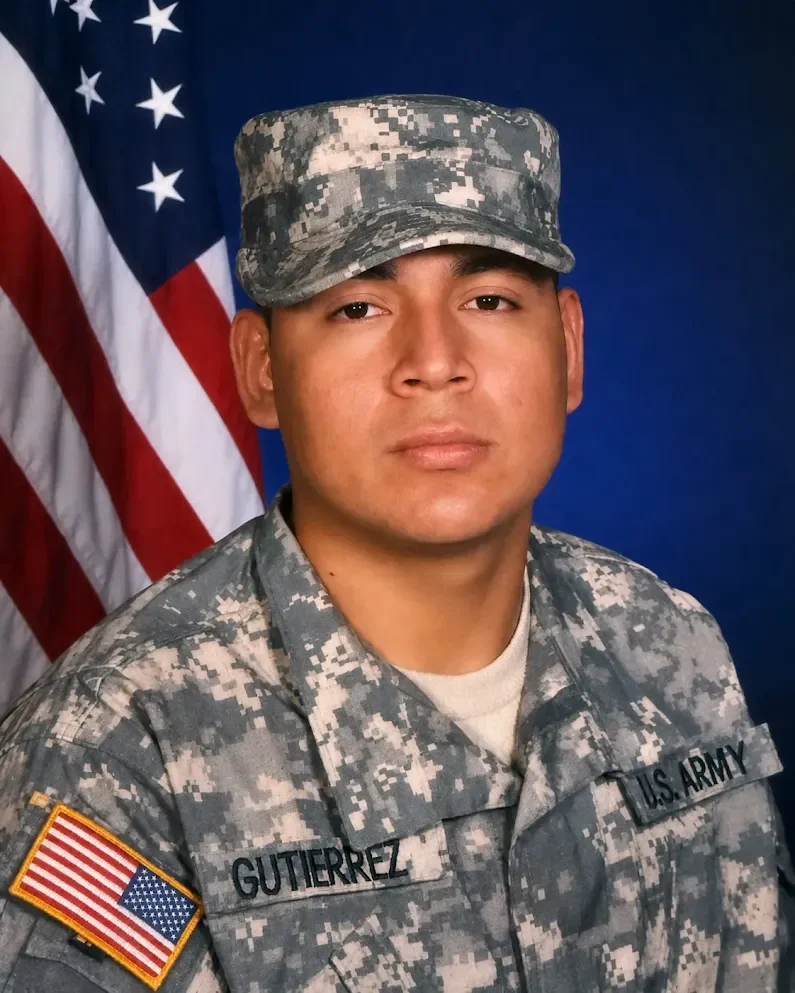
We Don’t Just Work With Veterans. We Are One.
Most agents will tell you they work with military and veteran clients. Here’s what makes this different.
Eight years in Army logistics meant moving people and equipment on hard deadlines with no room for a missed detail. That is not a bad description of a real estate closing either. When your contract has a date on it and your lender, your inspector, and the other side's agent all have to line up, Miguel has done that job before.
He used the VA loan to buy his own new construction home here in the Fort Bend County area, so when he walks you through entitlement, the funding fee, or what to expect from a VA appraisal, he is speaking from experience rather than from a training manual.
Jacob Shireman brings the marketing and negotiation side. Together they’ve helped Fort Bend County and Houston families through every stage of the process, from first-time buyers using their benefit for the first time to retirees relocating back to Texas.
Miguel also speaks Spanish, which matters in a market where a significant number of veterans and their families are more comfortable handling a transaction like this in their first language.
Schedule a ConsultationWhy Work With Us
Your Benefit Is Only Worth What Your Agent Understands About It.
The VA home loan is one of the strongest financing tools available to any buyer in this country, and it is routinely handled badly. Listing agents talk sellers out of accepting VA offers. Buyers get told they need money down when they don’t. Veterans with disability ratings pay a funding fee they were never required to pay.
We work these transactions constantly, and we know how to keep them from going sideways.
Buying With Your VA Benefit
Zero Down Is Real. Zero Dollars Is Not.
The VA loan lets qualified veterans, active duty service members, Guard and Reserve members, and some surviving spouses buy with no down payment and no monthly mortgage insurance. That part is true and it is a genuine advantage. These are the parts that decide whether your purchase actually goes smoothly.
Zero down does not mean zero out of pocket.
This is the misconception we correct most often. The VA loan eliminates your down payment, which on a conventional loan would run 3 to 5 percent or more. It does not eliminate every cost of buying.
You will need earnest money to secure the contract, typically around 1 percent of the purchase price, plus cash for your inspections. Earnest money is not an added fee. Assuming you close, it gets credited back toward what you owe at the table. It is your own money moving earlier in the timeline than most buyers expect.
Closing costs depend on how the deal is negotiated.
Closing costs are real, but who pays them is negotiable. Depending on the property, market conditions, and how we structure the offer, you might owe nothing additional at closing or walk away with money back. In a different deal you might bring funds. That outcome is a negotiation, not a fixed number, and it is one of the places where the right agent makes a measurable financial difference.
Your entitlement is reusable.
Using your VA loan once does not use it up. Entitlement can be restored after you sell and pay off the loan, and in some situations you can hold two VA loans at the same time. If you were told you already used your benefit, get a second opinion.
The funding fee may not apply to you.
Veterans receiving VA disability compensation are exempt from the VA funding fee. For everyone else, first-time use with no down payment runs 2.15 percent of the loan amount. On a Houston-area purchase that exemption is often worth several thousand dollars, so confirm your status before closing.
VA appraisals have their own rules.
The VA appraisal checks value and also verifies the home meets Minimum Property Requirements covering the roof, mechanical systems, wiring, and wood-destroying insect damage. We flag likely problems before you write the offer so you are not renegotiating repairs late in the deal.
Sellers are often wrong about VA offers.
There is a persistent myth that VA offers are slow and difficult. We know how to present your offer so it competes, and we handle the listing agent’s objections directly rather than letting them advise their seller against you.
Selling and Moving On
Retiring, Separating, or Relocating? We’ll Get You Positioned Right.
Whether you’re leaving the Houston area, moving across town after a change in circumstances, or selling a home you bought years ago with your benefit, the timeline is usually tighter than you’d like.
Your VA loan may be an asset when you sell.
VA loans are assumable by a qualified buyer, including buyers who are not veterans, with lender and VA approval. A 0.5% funding fee typically applies on an assumption. If you locked a rate well below today’s, that assumable loan is a genuine selling point that can move your home faster and at a stronger price — and most agents never bring it up. The caveat matters: unless the buyer is a veteran substituting their own entitlement, yours stays tied to that loan after closing, which limits what you can do on your next purchase. We work through that math with you before we market the feature.
Selling remotely.
If you’re already gone, we handle showings, coordination, repairs, and closing logistics without you having to fly back. That means walking the house ourselves, lining up and supervising contractors, managing photography and staging, and sending you a straight summary of feedback after every showing. Texas allows remote online notarization, so the paperwork travels to you — most of our out-of-area sellers never set foot back in the house after the movers leave.
Compressed timelines.
We’ll tell you honestly what your home can sell for in the window you actually have, and what a realistic price looks like if that window is short. Separation dates, report dates, and lease starts don’t move, so we build the plan backward from your hard date: what to fix, what to skip, and the list price that gets the house sold inside the calendar you’re working with rather than one that looks good on paper.
Texas Veteran Benefits
Texas Gives Veterans More Than Most States. Most People Don’t Use All of It.
Your federal VA benefits are only part of the picture. Texas layers additional programs on top, and two of them directly affect what you can afford here.
Disabled Veteran Property Tax Exemption
Texas offers a homestead property tax exemption for veterans with a service-connected disability rating. The exemption scales with your rating, and veterans rated 100 percent disabled or unemployable may qualify for a total exemption on the appraised value of their homestead. Surviving spouses may also qualify in certain circumstances.
In a state with no income tax and correspondingly high property taxes, this is often the single largest financial factor in a Houston-area veteran’s housing budget. It can change what price range makes sense for you, and it is frequently overlooked in the preapproval conversation.
Texas Veterans Land Board
The VLB offers home loans, land loans, and home improvement loans exclusively to Texas veterans, with interest rate discounts for veterans with qualifying disability ratings. Depending on your situation, a VLB loan may compete with or complement your VA loan.
We’ll walk you through which combination fits your circumstances and connect you with lenders who handle both.
Exemption tiers and VLB rate structures change by legislative session. We confirm the current figures with your lender before you build a budget around them.
Who This Is For
Every Path Into Houston Looks a Little Different.
Houston isn’t a big active-duty town, and that shapes who we work with. Most of our military clients fall into one of these situations.
Veterans already living in Houston
You’ve been here a while, your situation has changed, and you’re buying, selling, or using your benefit for the first time.
Separating or retiring from another Texas base
Coming out of Fort Cavazos, Joint Base San Antonio, or Fort Bliss and choosing Houston for the job market, the Medical Center, or family. We’ll help you time the purchase around your separation date and your first civilian paycheck.
Coast Guard Air Station Houston
Orders to Ellington Field come with almost no on-base housing and no large in-processing operation, which means you’re finding a home on the local economy with very little guidance. We know the commute corridors and the neighborhoods that work.
Guard and Reserve
Drilling with the 147th Attack Wing or a reserve component here in Houston. Guard and Reserve members qualify for VA loans after meeting service requirements, and a surprising number don’t know it.
Moving back to Texas
Out-of-state veterans relocating here for the cost of living, the absence of a state income tax, or proximity to the DeBakey VA Medical Center.
Where Houston Veterans Are Buying
We work across Fort Bend County and greater Houston. These are the areas that come up most often with our military and veteran clients, and why.
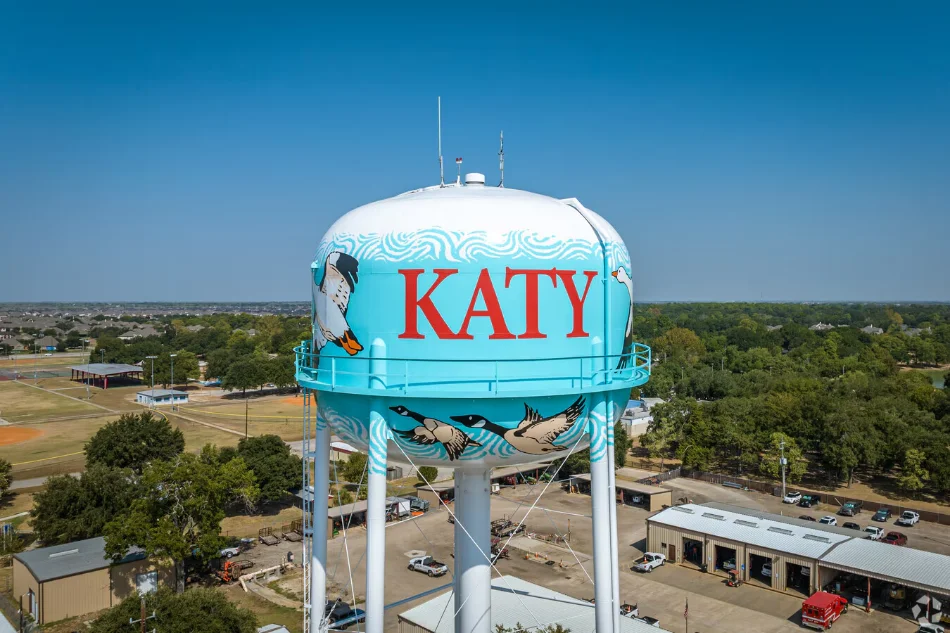
Katy, TX
Strong schools, new construction inventory, and reasonable access to the Energy Corridor.
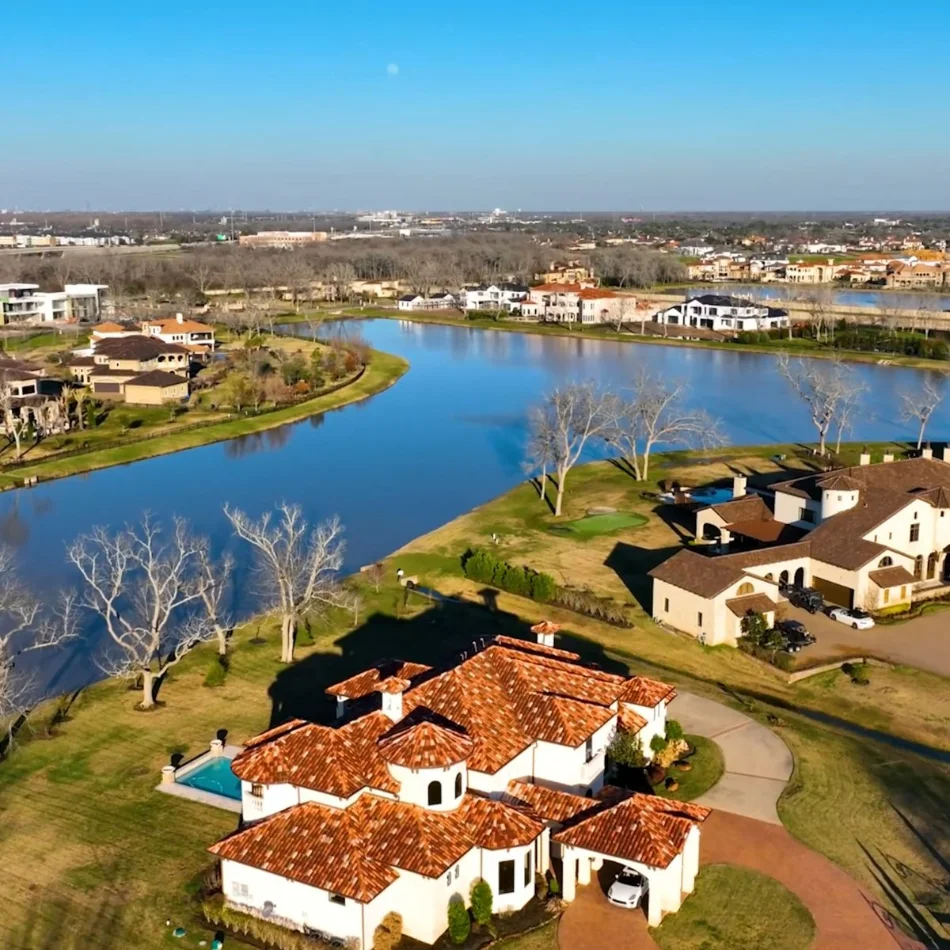
Richmond, TX
Value per square foot and space — popular with families buying their first home with a VA loan.
Fulshear, TX
Newer master-planned communities for buyers moving up.
Sugar Land, TX
Established neighborhoods and access to the Medical Center corridor.
Rosenberg, TX
The most affordable entry point in our service area.
Clear Lake / League City
Closest to Ellington Field and Coast Guard Air Station Houston.
¿Prefiere hablar en español?
Miguel habla español y trabaja con veteranos y sus familias en todo el área de Houston. Si prefiere manejar la compra o venta de su casa en español, podemos hacerlo desde el primer día hasta el cierre.
Hable con Miguel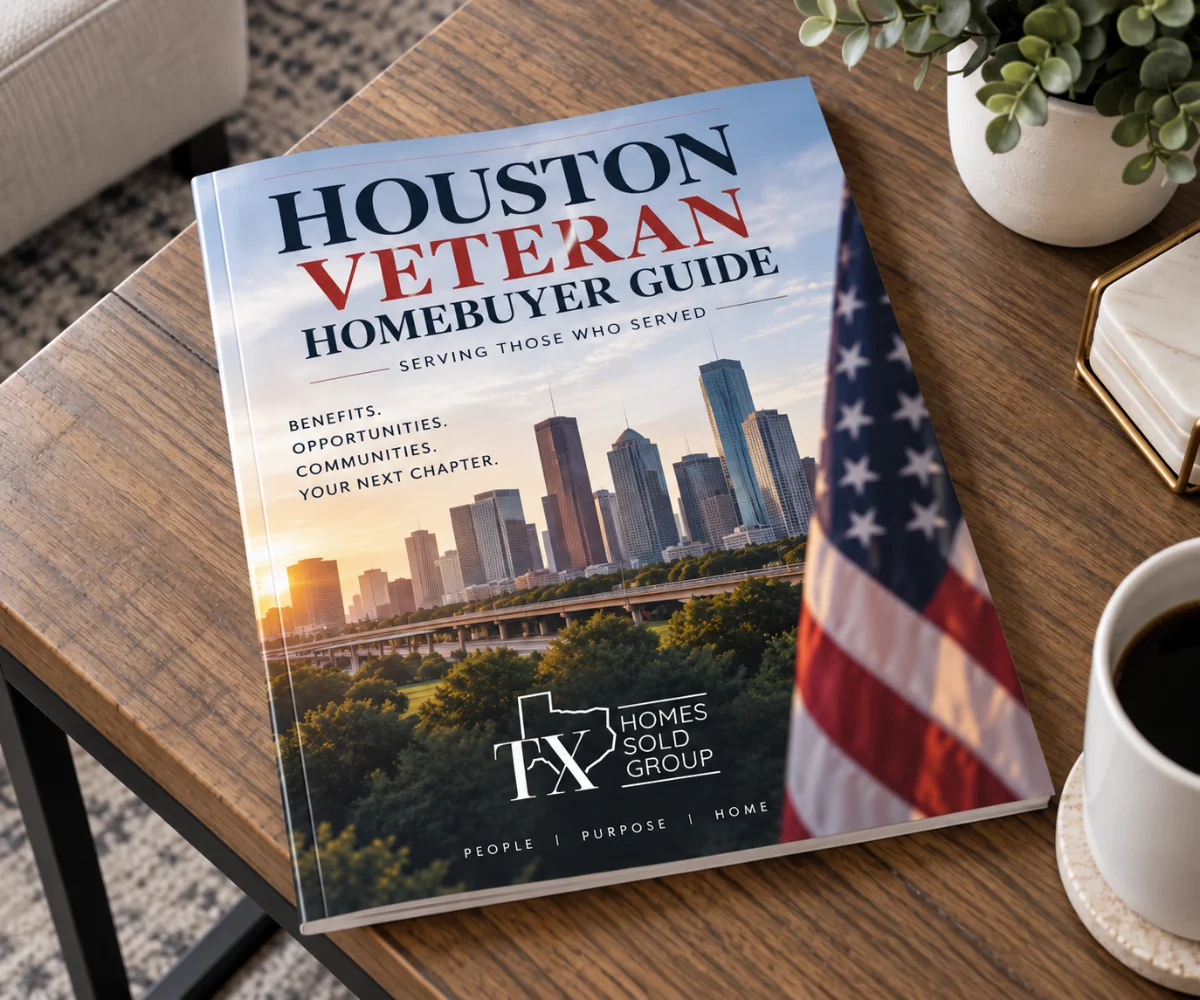
Free Download
The Houston Veteran Homebuyer Guide
Everything we walk our clients through, in one place. VA loan entitlement and how to reuse it, funding fee exemptions, what the VA appraisal actually checks, Texas disabled veteran property tax exemptions, Veterans Land Board programs, and a neighborhood breakdown across Fort Bend County and greater Houston.
Download the Free GuideFrom the Veterans We’ve Worked With
Common Questions From Houston Veterans
Yes. VA loan entitlement is reusable and does not expire. Once you sell the home and pay off the loan in full, you can apply to have your entitlement restored and use the benefit again. In some cases you can hold two VA loans at the same time using remaining entitlement, which matters if you are keeping a home as a rental and buying another in Houston.
If you were told you already used up your benefit, that is usually wrong. A lender can pull your Certificate of Eligibility and show you exactly how much entitlement you have left.
No. Veterans receiving VA disability compensation at any rating, surviving spouses of veterans who died in service or from a service-connected disability, and Purple Heart recipients are all exempt from the VA funding fee. For everyone else, a first-use purchase with no down payment carries a 2.15% fee, and subsequent use is 3.30%.
On a $350,000 Houston-area purchase, that exemption is worth roughly $7,500 at first use and over $11,500 on a subsequent loan. Confirm your exemption status before closing. If you were rated after closing, you may be able to request a refund of a fee you already paid.
There is no VA loan limit if you have full entitlement. Your borrowing amount is determined by what a lender approves based on income, credit, and debt-to-income ratio, not by a cap from the VA. Loan limits only apply if you have reduced entitlement because of an existing VA loan or a prior default.
In practice, Houston-area affordability is usually driven by property taxes rather than purchase price. Fort Bend County MUD districts can add significantly to a monthly payment, so two homes at the same price can carry very different costs. We factor that in before you write an offer.
Sometimes, and it is almost always based on outdated assumptions. Listing agents often believe VA loans close slowly or that VA appraisals kill deals. Modern VA loans close on comparable timelines to conventional financing, and the appraisal issues that used to cause problems are largely manageable when identified early.
The fix is presentation. We address the objection in the offer itself and speak directly to the listing agent before they advise their seller. In competitive Fort Bend County situations, that conversation is often the difference between an accepted offer and a rejected one.
A VA appraisal determines value and also verifies the home meets the VA’s Minimum Property Requirements. It checks for safe mechanical systems, a working heat source, adequate roofing, safe water and sewer, no exposed wiring, and no active wood-destroying insect damage. A conventional appraisal generally checks value only.
The VA appraiser is assigned by the VA, not chosen by your lender. If issues are flagged, they usually have to be corrected before closing. We identify likely MPR problems during showings so you are not renegotiating repairs two weeks before your closing date.
Texas exempts a fixed dollar amount from the appraised value of your property based on your VA disability rating: $5,000 for 10 to 29%, $7,500 for 30 to 49%, $10,000 for 50 to 69%, and $12,000 for 70 to 99%. Veterans awarded 100% disability compensation, either through a 100% rating or a determination of individual unemployability, receive a total exemption on 100% of the appraised value of their residence homestead.
The total exemption is the one that changes lives in Houston. On a $400,000 home in Fort Bend County with a combined rate near 2.5%, that is roughly $10,000 a year eliminated from your housing cost. Veterans 65 or older with a rating of at least 10% qualify for the $12,000 exemption regardless of their specific tier. Partial exemptions are filed on Form 50-135 and the total homestead exemption on Form 50-114 through your county appraisal district.
The Texas Veterans Land Board is a state program offering home, land, and home improvement loans exclusively to Texas veterans, separate from your federal VA benefit. The 2026 maximum home loan amount is $832,750, and veterans with a VA service-connected disability rating of 30% or higher receive a 0.50% interest rate reduction.
Which one fits depends on your situation. VLB also runs a land loan program that finances up to 100 acres, something a standard VA loan cannot do, so it is often the answer for buyers looking at acreage outside Richmond or Fulshear. VLB loans carry occupancy requirements: the home must be your Texas primary residence, you must occupy it within 60 days, and it must stay your primary residence for at least three years. VLB rates and program availability change, so confirm current terms at glo.texas.gov or with a participating lender.
Yes. Active duty service members can use the VA loan while still serving, and many buyers close before their separation date. Lenders can often use your military income to qualify, and in some cases a signed civilian job offer as well. The VA requires you to occupy the home as your primary residence, generally within 60 days of closing.
The timing question worth thinking through is income documentation. Closing while still on active duty is frequently simpler than closing during the gap between separation and your first civilian paycheck. If you are separating within the next year, it is worth talking to a lender early rather than waiting.
Yes. National Guard and Reserve members qualify for a VA loan if they meet the minimum service requirements set by the Department of Veterans Affairs. Eligibility is generally based on six years of qualifying service, or a shorter period of active duty service under Title 10 or Title 32 orders. Discharge conditions and service dates matter, so eligibility is confirmed through your Certificate of Eligibility.
This is one of the most commonly missed benefits in Houston. Members drilling with the 147th Attack Wing at Ellington Field and reserve components across the metro frequently assume the VA loan is for active duty and veterans only. It is not.
Yes. VA loans are assumable by a qualified buyer, including buyers who are not veterans, subject to lender and VA approval. A 0.5% funding fee typically applies on an assumption. In a market where current rates sit well above what many homeowners locked in, a low assumable rate can be a real competitive advantage when you list.
The critical caveat: if the buyer is not a veteran substituting their own entitlement, your entitlement stays tied to that loan even after you sell, which limits your ability to use your benefit on your next purchase. Assumption can be the right move or the wrong one depending on whether you plan to buy again. Work through that before you market the feature.
Yes. Remote sales are routine. We handle pre-listing repairs and vendor coordination, photography and staging, showings and feedback, offer negotiation, inspection response, and closing logistics. Texas allows remote online notarization and most closings can be completed without you traveling back.
Give us as much lead time as you can. A home prepared properly before it hits the market almost always nets more than one listed in a hurry, even accounting for a few extra weeks of carrying costs.
Sí. Miguel habla español y puede manejar todo el proceso — desde la primera consulta hasta el cierre — en español, incluyendo la explicación de su beneficio VA y los documentos del préstamo.
Let’s Talk About What You’ve Earned.
Whether you’re using your VA benefit for the first time, selling before a move, or just trying to figure out what’s actually possible in this market, start with a conversation. No pressure and no obligation.